The Hidden Emotional Toll of Managing Family Wealth After a Loss
in this exact same nightmare right now, take a deep breath. Let me show you how to survive this mess and protect your family's money without losing your mind.
Every time my phone rang, it was another family member asking when they would receive their share of the payout. The pressure was suffocating, making an already painful situation feel entirely impossible. I felt completely paralyzed by the fear of making a massive mistake.
I constantly worried that checking the wrong box on a single insurance claim form would cost my family thousands of dollars. Sleep became a rare luxury, quickly replaced by endless nights of reading confusing legal terms online. I realized very quickly how this exact struggle breaks families apart every single day.
The heavy stress of handling inherited money can turn siblings against each other in the blink of an eye. People who love each other deeply suddenly argue over percentages, legal fees, and payout timelines. The heavy emotional weight of this entire process drains your energy entirely.
What You Will Learn In This Guide:
- How to stop insurance companies from delaying your family’s payout.
- The safest way to organize paperwork so you never lose important documents.
- Exactly why you need a 6-month "cooling off" period before spending inherited money.
- How to avoid the hidden tax traps that wipe out sudden wealth.
Breaking Down the Wall of Confusion Around Estate Assets
Handling the financial aftermath of a loss is never a simple journey. You need a clear and practical roadmap to clear the heavy fog of confusion. Let us break down exactly how you can manage this situation smoothly and keep your family united.
Why the Claiming Process Feels Like a Maze
When you first start dealing with insurance companies and banks, it feels like they are speaking a completely different language. They throw forms at you with strange acronyms and ask for documents you have never even heard of. This is completely normal, and you are not alone in feeling lost.
Most financial institutions have strict rules to prevent fraud, which sadly makes the process incredibly slow for honest families. They require original death certificates, notarized identity proofs, and perfectly filled-out claim forms. If you miss just one signature, your entire application gets sent to the back of the line.
To avoid this exhausting cycle, you need to understand exactly what these companies actually want from you. They just want absolute proof that they are giving the money to the right person. Once you understand this basic fact, their demanding behavior starts to make a lot more sense.
Avoid The Biggest Payout Mistakes Early On
Watch this short video before you sign any official documents to ensure you do not accidentally forfeit thousands of dollars in hidden fees.
The Reality of Dealing with Insurance Providers
There are many wild rumors about how insurance companies handle large payouts. It is incredibly important to separate facts from fiction before you make your first phone call. Let us look at a quick comparison between common beliefs and the actual reality.
Myth vs Reality: Understanding Payouts
- The Myth: The insurance company will automatically send a check to the family right after someone passes away.
- The Reality: No company will send money automatically. You must actively file a formal claim and provide heavy documentation to start the process.
- The Myth: The payout will always match the exact face value of the policy.
- The Reality: Unpaid premiums, outstanding policy loans, or administrative fees can significantly reduce the final payout amount.
Practical Strategies for Managing Complex Beneficiary Rules
Understanding who gets what is usually the biggest source of family arguments. The legal documents often tell a very different story than what your loved one promised verbally. Navigating this difference requires patience, logic, and extreme care.
Organizing the Paperwork Without Losing Your Mind
Before you can divide any money, you need to know exactly what exists. You cannot manage a payout if you cannot find the actual policy document. You must treat this situation like an important administrative job.
Dedicate one single, safe place in your home for all estate-related documents. Buy a sturdy accordion folder and label every single section clearly. Keep all banking details in one pocket, insurance policies in another, and legal certificates in the front.
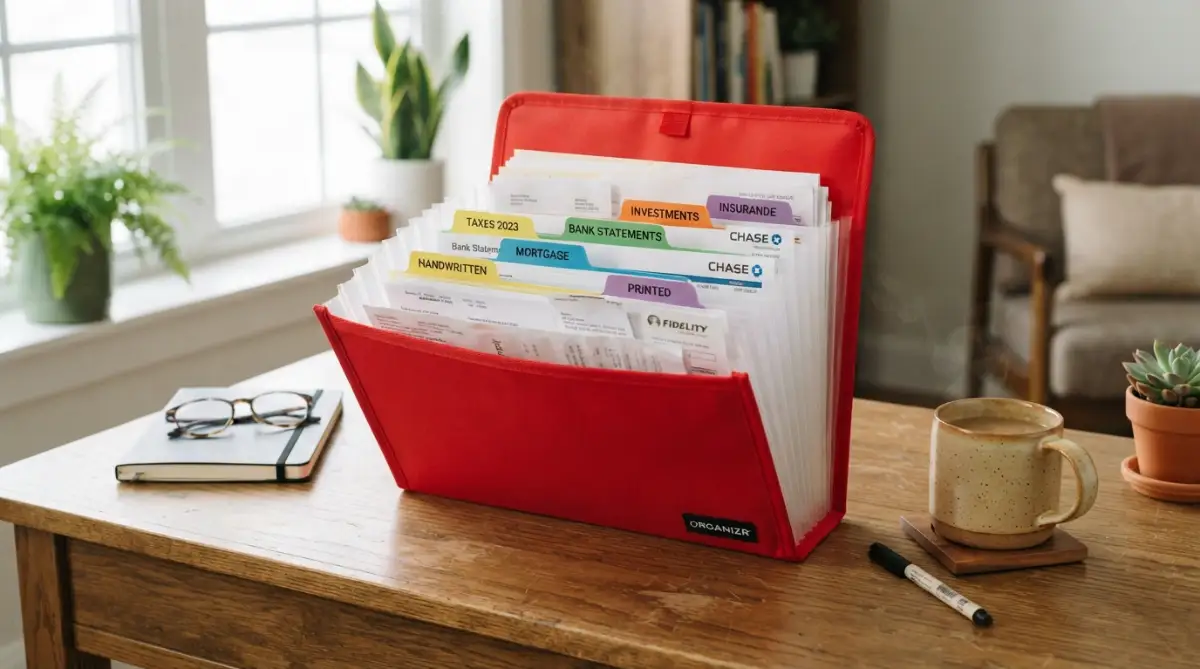
I highly recommend buying a fireproof safe for the original copies of the most important documents. You should also scan every single piece of paper and save it to a secure cloud drive. Having a digital backup will save you an incredible amount of stress if a physical document gets misplaced.
My Personal Pro Tip: I learned this the hard way when I lost the original death certificate right before a major bank meeting. I had to wait three weeks for the city to issue a new one, which delayed our payouts terribly. Always order at least ten original copies of the death certificate on the very first day, and keep them in a bright red folder that you can never miss.
My Quick "Day 1" Survival Checklist:
- Get 10+ original death certificates (trust me, everyone asks for an original).
- Find the actual physical will or trust documents.
- Locate recent bank statements (just the last 3 months is fine for now).
- Track down the passwords for their main email and phone.
Understanding How Different Payout Structures Work
Not all payouts come as a single, large sum of money. Depending on the specific policy, you might have to make a choice about how you receive the funds. Making the wrong choice here can deeply impact your financial future.
Sometimes, taking the money slowly over time is much safer than taking it all at once. Let us look at a simple breakdown of the two most common ways to receive a large payout.
You should never rush this specific decision. Sit down with a calculator and figure out your actual living costs before choosing an option. Once you select a payout method and sign the final papers, you can almost never reverse that decision.
Keeping the Peace When Dividing Inherited Assets
Money has a terrifying ability to change how people treat each other. When an estate is finally settled and the payouts are ready, tensions are usually at an all-time high. You must handle this final step with absolute transparency to protect your family relationships.
The Power of Transparent Communication
The fastest way to start a family feud is by keeping secrets. If you are the person managing the estate, you hold a lot of power, which naturally makes others suspicious. You must actively work to remove that suspicion every single day.
Set up a simple group chat with all the beneficiaries involved in the estate. Send them short, regular updates even if nothing major has happened that week. A quick message saying, "Still waiting on the bank, I will call them on Tuesday," goes a very long way.
When people feel included in the loop, they are far less likely to become angry or impatient. They just want to know that you are actively working on the situation. Silence is the ultimate enemy of family unity during an estate settlement.
When to Hire a Neutral Third Party
Sometimes, a family history is just too complicated to handle internally. If arguments are already starting, do not try to play the role of the peacemaker yourself. You are too close to the situation to remain completely unbiased.
Bringing in a professional mediator or an independent financial advisor can completely change the atmosphere. When a neutral professional explains why a payout is delayed, family members listen differently. They cannot accuse an outsider of playing favorites.
Yes, hiring a professional will cost some money upfront. However, this small cost is nothing compared to the legal fees of a bitter family lawsuit. Protecting your family's emotional bond is worth the price of a good mediator.
Navigating the Invisible Threat of Taxes
Many people mistakenly believe that whatever money they inherit is entirely theirs to keep. This dangerous assumption can lead to a massive financial shock during the next tax season. You must approach inherited money with a heavy dose of financial caution.
Protecting Your Sudden Wealth from Unexpected Fees
Depending on where you live, the government might want a piece of your payout. Life insurance is usually tax-free, but other inherited accounts like retirement funds are completely different. Withdrawing money from an inherited retirement account can trigger massive income taxes.
Think of your new inheritance like a sudden, unexpected business profit. You would never spend a business profit without setting aside money for the tax authorities first. You need to treat your personal estate payout with that exact same level of discipline.
I always advise people to put at least twenty percent of any complex payout into a separate, high-yield savings account. Do not touch this specific money for an entire year. If a surprise tax bill arrives, you are perfectly prepared to pay it without panic.
Reality Check: Did you know that taking a lump sum from an inherited IRA can bump you into a completely different tax bracket overnight? My friend Sarah made this mistake last year and lost almost 35% of her inheritance to surprise taxes. Always ask your accountant about the "10-year rule" before moving a single dollar.
Working with the Right Professionals
You do not have to figure out these complex tax rules by yourself. In fact, trying to be your own tax expert is a recipe for disaster. The tax codes change constantly, and missing one small update can result in heavy penalties.
Find a certified accountant who has specific experience dealing with estate payouts. They can look at your specific situation and tell you exactly what you owe. A good accountant will often save you far more money than they actually charge you in fees.
Mastering the Next Phase of Family Wealth Management
Once you survive the initial shock of filing paperwork, the real work begins. Managing a large financial payout requires a completely different set of skills than simply organizing legal forms. You are now stepping into the role of a family financial guardian.
I want to share some advanced strategies that professionals use to keep wealth intact. These are the exact methods that wealthy families use to prevent money from slipping through the cracks. Applying these concepts to your own situation will save you incredible amounts of stress.
The Power of the Six-Month Cooling Off Period
When a large sum of money suddenly hits your bank account, your brain goes into overdrive. You might suddenly feel the urge to buy a new house, quit your job, or invest in a risky business. This sudden rush of adrenaline is exactly why so many people lose their inherited money quickly.
My biggest piece of advice is to enforce a strict six-month waiting period on yourself. Put the money into a safe, high-yield savings account and refuse to touch it. Give your mind enough time to calm down and process the emotional loss of your family member.
During this waiting period, you will clearly see the difference between what you want and what you actually need. You can use this time to carefully read through resources like the official guidelines on managing a sudden influx of wealth to prepare your next steps. Patience is truly your greatest financial weapon right now.
Setting Up a Dedicated Estate Bank Account
Never, under any circumstances, mix your personal money with the estate's money. When you mix funds, tracking down specific expenses becomes an absolute nightmare. You need a clear boundary between your daily life and your legal responsibilities.
Go to a local branch and open a checking account specifically named for the estate. Every single payout, refund, or insurance check must go directly into this specific account. When you need to pay a lawyer or settle a final medical bill, you write the check exclusively from here.
This simple step creates a perfect paper trail for everyone involved. If a family member ever questions how you are spending the money, you can simply print out the clean bank statement. Absolute transparency completely destroys any room for suspicion or arguments.
Taking Control of Hidden Digital Assets
We live in an era where much of our wealth is completely invisible. People often forget that their loved ones had PayPal balances, online investment accounts, or even cryptocurrency. Finding these hidden assets is often the most challenging part of the entire settlement.
Start by legally accessing their primary email account, which acts as the master key to their digital life. Look for monthly subscription receipts, digital bank statements, or password recovery emails. You can often discover entirely separate savings accounts just by looking through their inbox history.
If you are unsure of your legal rights regarding digital accounts, you should read the expert guides on navigating the digital probate process to protect yourself. Many tech companies have strict rules about who can access an account after someone passes away. Handling this carefully ensures you do not accidentally lock the family out of valuable funds.
The Truth About Appraisals and Physical Property
Sometimes a payout does not come in the form of a clean bank check. Often, a massive portion of the family wealth is tied up in houses, antique furniture, or old family businesses. You cannot easily divide a house among three siblings without a clear plan.
Do not try to guess the value of a property based on online searches. You must hire a certified, independent appraiser to put an official price tag on physical assets. An official document prevents family members from arguing over what a property is actually worth.
Once everything is officially priced, you can start making fair decisions. Maybe one sibling keeps the family home, while the other takes the equivalent value in cash from the insurance payout. Making decisions based on hard data keeps the peace much better than making emotional guesses.
Protecting Your Own Financial Stability First
While managing an estate, it is very easy to forget about your own financial health. You might find yourself missing work, spending your own savings on travel, or neglecting your personal bills. You cannot pour water from an empty cup.
If the settlement involves clearing old debts, you might suddenly face the reality of understanding how to handle overwhelming student loans left behind by the deceased. Never use your personal emergency fund to pay off someone else's legal obligations. The estate itself must cover those costs.
If you are asked to take on financial burdens during this time, be extremely careful. You must recognize the warning signs before taking on a shared family loan to protect your newfound stability. Protecting your personal credit score must remain your top priority throughout this entire ordeal.
Hidden Traps That Destroy Family Fortunes
Even with the best intentions, families fall into the same predictable traps every single day. These mistakes do not just delay the settlement process; they completely destroy lifelong relationships. Let us look closely at what you must absolutely avoid at all costs.
Distributing Money Before Paying the Final Taxes
This is easily the most dangerous mistake any estate manager can make. Imagine handing out fifty thousand dollars to your siblings, only to receive a massive bill from the government months later. If the estate account is empty, you are legally responsible for paying that tax bill out of your own pocket.
Many people do not understand that certain types of accounts are heavily taxed upon withdrawal. For example, you should always check the official tax rules for inherited retirement accounts before moving any money. Ignorance of the law will not save you from government penalties.
Always keep a large percentage of the cash firmly locked in the estate account until the next major tax season has passed. Tell your family directly that this is a legal requirement, not a personal choice. A little disappointment today is much better than a massive lawsuit tomorrow.
Fighting Bitter Battles Over Small Sentimental Items
Money is rarely the thing that actually breaks a family apart. Often, siblings will agree perfectly on dividing a huge bank account but will go to war over an old wooden rocking chair. Grief makes people project their heavy emotions onto small, meaningless physical objects.
I have seen families spend thousands of dollars in legal fees arguing over a cheap piece of jewelry. You have to ask yourself if being "right" is worth destroying your relationship with your sister or brother. Sometimes, letting go of a small item is the smartest financial and emotional decision you can make.
If two people want the same item, try setting up a private family auction. Whoever wants the item the most can buy it from the estate, and that cash is then divided equally among everyone. This system forces people to decide how much an item actually means to them.
Ignoring Hidden Gaps in Insurance and Policies
You might assume that the payout you received is the absolute final amount available. However, many people leave behind multiple policies that their families simply never knew about. You must dig deep into their paperwork to ensure you are not leaving money behind.
Review their medical history and previous coverage very carefully. You might uncover hidden gaps in a standard health insurance plan that explain why certain surprise medical bills were left unpaid. Knowing the truth helps you negotiate down those final hospital debts effectively.
Also, check if they held any supplementary life coverage at their workplace. Understanding the truths about outliving a standard term policy can help you figure out exactly what benefits expired and what is still valid. Do not let the insurance company keep money that rightfully belongs to your family.
Sometimes, an unexpected estate settlement is triggered by a sudden, tragic accident. If you ever find yourself dealing with the aftermath of a minor vehicular accident requiring immediate steps, handling the associated insurance claims perfectly is your first line of defense. Look into all auto policies as well, because uninsured motorist coverage can secretly save your finances if a careless driver was involved.
Rushing the Process Just to Get It Over With
The emotional weight of an estate settlement makes you want to finish it as fast as physically possible. You just want the phone calls to stop so you can finally go back to your normal life. However, rushing legal paperwork always leads to very expensive disasters.
Take things one single step at a time, even if it feels incredibly slow. If a bank tells you it will take four weeks to review a document, accept that timeline peacefully. Pushing them to work faster will only cause them to reject your paperwork over a tiny spelling mistake.
Always keep your family updated on these slow timelines so they adjust their expectations. I recommend directing highly impatient family members to trusted resources on organizing family affairs so they understand the heavy workload you are managing. When they see how complex the rules are, they usually become much more understanding.
Your Immediate Action Plan for Tomorrow
Managing a complex family estate is never a fun experience, but it is deeply honorable work. You are protecting your family's future and ensuring your loved one's final wishes are respected. Let us look at a simple, positive action plan to keep you moving forward.
First, take a deep breath and forgive yourself for feeling overwhelmed. No one is naturally good at managing massive legal payouts without prior experience. You are learning on the job, and it is completely okay to make a few small stumbles along the way.
Tomorrow morning, start by setting up that dedicated estate bank account. Gather all the official death certificates in one physical folder and secure your digital backups. Once the administrative foundation is strong, everything else becomes significantly easier to handle.
Keep the lines of communication wide open with every single beneficiary. Remember that they are grieving too, and their impatience usually comes from a place of deep pain, not greed. Lead your family with kindness, transparency, and a strong sense of logic.
A Personal Word Before You Go: I know exactly how incredibly heavy this burden feels on your shoulders right now. My own journey through this process tested every ounce of my patience, but taking it one simple form at a time eventually brought me total peace. I promise you that if you stay organized and communicate honestly, you will guide your family through this dark time successfully.
Clear Answers to Your Biggest Payout Questions
How long does a typical estate settlement process actually take?
Every single situation is different, but a standard settlement easily takes anywhere from nine to eighteen months. Complex estates involving multiple properties or missing wills can drag on for several years. You should always prepare your family for a very slow, methodical legal process.
Do I have to pay taxes on a life insurance payout?
In most common scenarios, a direct life insurance death benefit is completely free from income tax. However, if the insurance money earns interest in a bank account before it is distributed, you will owe taxes on that specific interest. Always check with a local tax professional to be absolutely sure.
What happens if a family member refuses to sign the settlement papers?
A stubborn beneficiary can definitely freeze the entire process, preventing anyone else from getting their share. In these tough situations, you will likely need to bring in a professional mediator or an estate lawyer to intervene. Usually, an official letter from a lawyer quickly convinces people to cooperate.
Can the estate manager charge a fee for their hard work?
Yes, the person actively acting as the executor is legally allowed to take a reasonable fee for their time and effort. This fee is paid directly out of the estate funds before the final money is divided among the family. You must keep perfect records of your working hours to justify this payment.
What should I do if the deceased left behind massive credit card debt?
You are generally not personally responsible for paying their credit card bills with your own money. Those specific debts are paid strictly out of the estate's total value before any heirs receive their final payouts. If the estate runs out of money before all debts are paid, the credit card companies simply have to take the loss.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial, legal, or tax advice. Every estate settlement is highly unique and subject to specific local laws. Always consult with a certified financial planner, estate attorney, or tax professional before making any major decisions regarding inherited wealth or legal payouts.