The Hidden Weight of Managing an Inherited Mess
Dealing with a messy estate after losing someone isn't just emotionally draining—it's a bureaucratic nightmare. Suddenly, you are staring at a massive stack of insurance papers, confusing legal jargon, and automated phone menus that go nowhere. Let's cut through the noise and look at exactly how you can force these companies to pay out without losing your mind in the process.
I felt an overwhelming sense of dread mixed with my raw, painful grief. It honestly felt like the heavy weight of the world was resting directly on my shoulders. Figuring out my way through that frustrating maze changed how I view family settlements forever. I realized that the people supposed to help you often make things harder.
When you lose someone you love, the last thing you want to do is argue with an insurance company. You are already mentally exhausted, yet the daily reality of managing an estate forces you to be sharp. Normal people face a massive wall of legal terms and confusing requirements that drain their energy.
You try to go to work, take care of your kids, and mourn your loss, but the phone calls never seem to stop. The insurance agents ask for papers you cannot find, and family members start asking uncomfortable questions about money. This constant pressure easily ruins your daily peace of mind and steals your sleep at night.
What You Need to Know Upfront (Key Takeaways):
- The policy beats the will: Life insurance payouts follow the beneficiary form, not what is written in a final will.
- Track everything: Write down every agent's name, time of call, and exact promises made during phone calls.
- Prepare for standard delays: Even perfect, error-free claims typically take 30 to 60 days to hit your bank account.
- Protect minor children: Kids cannot directly inherit cash; you will need legal guardianship accounts set up through a court.
Breaking Down the Bureaucracy Wall
Handling an estate is completely different from getting a simple car insurance check. You need to understand exactly what you are dealing with before you make your first phone call. Most families fail right at the beginning because they do not know what questions to ask.
Insurance companies have very strict rules for paying out large sums of money. They will not guide you by the hand; you have to take charge of the situation yourself. Let us look at exactly how you can take back your power and speed up this painful process.
Finding the Missing Pieces of the Puzzle
Your very first job is to become a detective in your own home. Most people do not keep all their important policies in one neat little folder. You will probably have to search through old filing cabinets, safe deposit boxes, and even computer hard drives.
Look closely for any old bank statements showing automatic monthly payments to an insurance provider. Sometimes, a simple $20 monthly charge is the only clue you have that a massive policy exists. Call those companies immediately and ask for a complete copy of the policy to be mailed to you.
Once you have the documents, you need to find the specific page listing the named beneficiaries. This is where things often get incredibly messy for families. If the named beneficiary is an ex-spouse from decades ago, you will need legal help immediately.
Understanding Beneficiary Designations vs. The Will
Here is a shocking fact that catches many families totally off guard. A life insurance beneficiary designation almost always overrides whatever is written in the person's final will. You might have a will saying everything goes to you, but the policy says something else.
If your parent named your older sibling as the sole beneficiary on the insurance document, the money belongs to them legally. The insurance company does not care what the will says, and they do not care about verbal promises. This simple misunderstanding destroys relationships and starts massive arguments at the dinner table.
Knowing this rule ahead of time can help you manage your family’s expectations before the anger starts. Always read the beneficiary forms carefully before you promise anyone a share of the money. Being honest and clear with your relatives early on is the best way to prevent future drama.
Quick Check: Beneficiary Form vs. The Will
Here is a fast breakdown of what actually happens when your documents contradict each other:
| Scenario | Who Gets the Money? | Why? |
| :--- | :--- | :--- |
| Will says "Spouse", Policy says "Child" | The Child | The insurance policy is a separate binding contract. |
| Will says "All Kids", Policy says "Ex-Spouse" | The Ex-Spouse | Outdated beneficiary forms always win, even decades later. |
| Policy has no named beneficiary | The Estate | The money goes to probate court, and the Will finally takes over (expect long delays). |
How to Talk to Difficult Insurance Adjusters
When you finally call the claims department, remember that they are recording every single word you say. Never guess the answer to a question if you are not completely sure about the facts. It is perfectly fine to say, "I need to check my records and call you back."
Keep a dedicated notebook right next to your phone for these specific conversations. Write down the date, time, and the name of the agent you speak with during every single call. If they promise to send you a specific form by Tuesday, you need a record of who made that promise.
My Personal Advice: I made a huge mistake early on by trying to handle everything over the phone without writing things down. I quickly learned that following up every phone call with a quick email summarizing our conversation saved me hours of repeating myself. Having things in writing is your strongest weapon against delays.
[Here is exactly why you need to record your interactions and how it saves your family from legal headaches later.]
The Reality of "Incontestable Clauses"
Insurance policies have a specific rule that protects the company during the first few years of the contract. If the person passed away shortly after buying the policy, the company will investigate the claim heavily. They want to make sure no one lied on the original application regarding their health.
This investigation process can legally delay your family’s money for many months. Do not panic if they start asking for detailed medical records from five years ago. This is a standard procedure, but it requires you to be highly organized and patient.
You will need to contact doctors and hospitals to get these records released to the insurance investigators. Always make copies of the medical records before you send them away in the mail. If the post office loses your package, you do not want to start the whole process over again.
Myth vs Reality: The Speed of Payouts
Let us clear up some common misunderstandings about how fast you will actually get paid.
- The Myth: You will receive a check two days after you submit the death certificate.
- The Reality: Even clean, simple claims take up to thirty days to process and pay out.
- The Myth: The insurance company will notify all family members automatically.
- The Reality: They only communicate with the person officially managing the claim, usually the primary beneficiary.
- The Myth: The payout is heavily taxed by the government right away.
- The Reality: In most cases, basic life insurance payouts are completely tax-free for the person receiving them.
Understanding these realities helps you plan your personal finances better while you wait for the settlement. You might need to cover funeral expenses out of your own pocket temporarily. Knowing the true timeline stops you from refreshing your bank account every single morning in frustration.
Real-World Example:
My friend Sarah submitted a perfectly clean claim last year. She assumed she would get a direct deposit by Friday. Instead, it took exactly 38 days. Why? The insurance company spent 14 days just verifying the death certificate with the state, another 10 days reviewing the policy history, and 14 days actually clearing the funds through their finance department. Expect a 30 to 60-day window, and plan your immediate funeral budgets around that reality.
Handling Disagreements Without Tearing the Family Apart
Money has a terrible habit of bringing out the absolute worst in people we love. When grief mixes with a large sum of cash, brothers and sisters can quickly turn into enemies. Your job is to keep communication completely open and transparent from day one.
Consider setting up a weekly family meeting to give everyone an exact update on the settlement progress. Share the letters you receive from the insurance company so everyone sees you are not hiding anything. Transparency builds trust, and trust is what keeps your family united during a crisis.
If a disagreement gets too heated, do not try to win the argument by yelling louder. It is highly recommended to bring in a neutral third party, like a professional family mediator. Sometimes, hearing the exact same information from a professional calms everyone down immediately.
The Hidden Dangers of Minor Beneficiaries
Things get incredibly complicated if a minor child is listed to receive a portion of the payout. Insurance companies absolutely will not hand a massive check directly to an eight-year-old child. They also will not just hand it to the surviving parent without proper legal steps.
You will usually have to go to the local courthouse and set up a legal guardianship account. A judge must officially approve whoever is going to manage that money until the child grows up. This process takes time, requires expensive court fees, and involves a lot of confusing legal paperwork.
If you are dealing with minor beneficiaries, you cannot do this alone through simple phone calls. You must hire an expert who deals with family estates to guide you through the court system safely. Trying to skip this step will just get the funds permanently frozen by the insurance company.
Creating Your Bulletproof Document Checklist
Every time you interact with the claims department, they will ask for proof of everything. If you are missing just one signature, your file goes straight back to the bottom of the pile. Creating a master file at home will save your sanity.
Here is what you need to gather immediately:
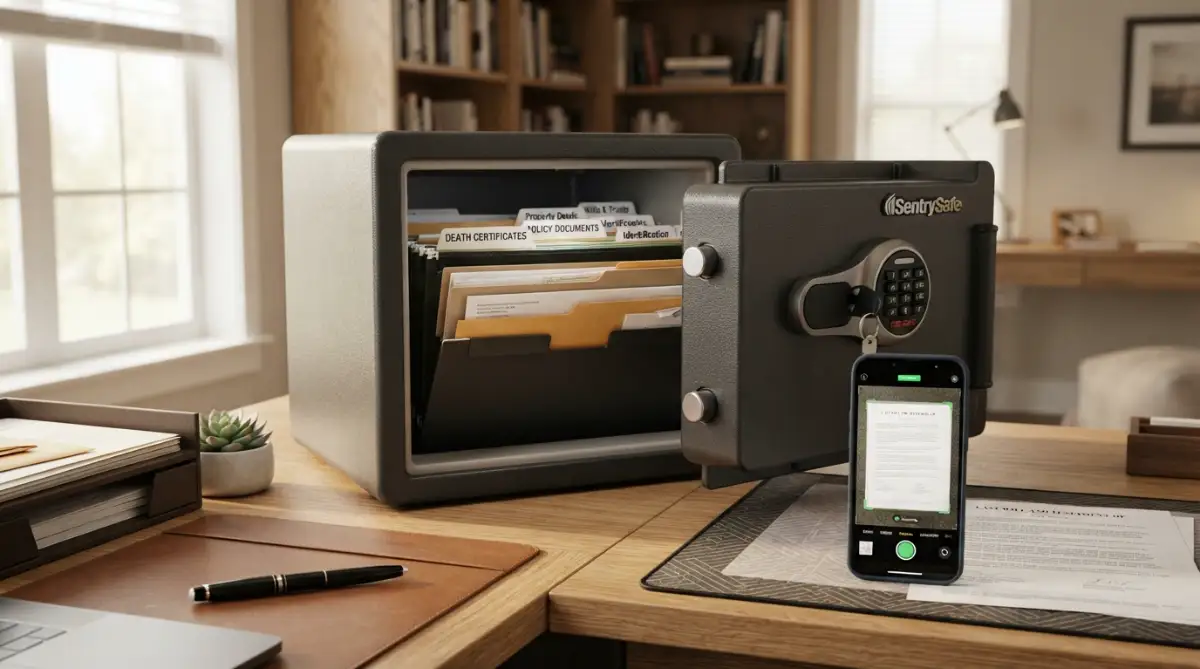
- At least five original, certified copies of the death certificate.
- The original insurance policy documents, not just photocopies.
- Your own government-issued ID and social security information.
- The legal documents naming you as the executor, if applicable.
Keep all of these originals in a fireproof safe, and make a digital scan of everything for your phone. When the claims adjuster asks for a copy, you can email it to them in less than three minutes. Speed and organization are your best friends when you are trying to force an insurance company to pay quickly.
Dealing with Multiple Policies and Different Companies
Many people buy multiple smaller policies throughout their life instead of one massive policy. You might find yourself dealing with three completely different insurance companies at the exact same time. Each company has its own unique forms, specific rules, and processing timelines.
Do not try to memorize everything in your head; you will definitely burn out. Create a simple spreadsheet on your computer to track each policy separately. Add columns for the company name, policy number, claim status, and the date of your last contact.
This visual dashboard helps you see exactly where you are stuck and who you need to call next. When you wake up feeling overwhelmed, just look at your spreadsheet and tackle one single task. Breaking a massive problem down into small, daily steps makes the entire journey highly manageable.
Protecting the Payout Once It Arrives
After months of hard work, phone calls, and stress, the money will finally hit your bank account. Take a deep breath and give yourself permission to feel proud of what you just accomplished. However, the worst mistake you can make now is spending it instantly without a clear plan.
Sudden wealth can be incredibly confusing, and you might feel pressured to pay off all your debts today. Do not make any major financial decisions for at least three to six months after receiving the money. Put the funds into a safe, high-yield savings account and just let it sit there while your emotions settle.
Talk to a certified financial planner who has zero connection to your personal family drama. They will help you understand how to invest the settlement so it protects your own future. Your loved one left you this money to give you security, not to cause you anxiety. Taking things slow ensures you honor their memory by using the settlement wisely.
Next-Level Strategies for Securing Your Inherited Wealth
Let us talk about the absolute long game of managing a large financial windfall. Once you get past the initial shock and the mountain of paperwork, you have to start thinking like a professional wealth manager. Most families completely ignore the long-term impact of suddenly receiving a massive payout, which is a huge mistake.
If you just leave the money sitting in a standard, low-interest checking account, inflation will slowly eat away at its true value. You worked entirely too hard fighting the insurance company to let your money lose its purchasing power. This is the perfect time to build a solid financial fortress for your own children and grandchildren.
Building a Protective Shield Around Your Money
One of the smartest moves you can possibly make is setting up a specialized family trust account. Unlike a simple paper will, a trust gives you incredible, detailed control over exactly when and how the money gets spent over time. It actively protects the funds from future lawsuits, messy divorces, or poor financial choices made by young adults in your family.
I highly recommend consulting with a certified estate attorney to draft these specific documents properly in your state. Trying to download a cheap legal template from a random internet site is a massive recipe for disaster. Taking this step seriously is a lot like avoiding the hidden traps when outliving a term policy; you simply need expert guidance to stay safe.
The Secret Power of Tax Professionals
While basic life insurance payouts are usually completely tax-free, the interest that money earns sitting in the bank is definitely not. If the payout takes six months to process, the insurance company actually owes you interest for that long delay. That extra interest money is completely taxable by the federal government, and they will absolutely come looking for their share.
Do not ever try to guess your way through the confusing tax code on your own without professional help. Hiring a certified public accountant (CPA) will easily save you from terrifying audits down the road. You can actually verify the specific estate tax rules directly through the official IRS estate planning guidelines to stay highly informed and prepared.
Hunting for Forgotten Family Assets
Here is a massive secret that insurance agents rarely mention during the standard settlement process. People often leave behind hidden bank accounts, old retirement funds, and random stock dividends that the family knows absolutely nothing about. These missing funds eventually get turned over to the state government as "unclaimed property" if no one comes looking for them.
You should make it a strict habit to check the National Association of Unclaimed Property Administrators (NAUPA) website every single time you review your finances. Just type in your loved one's full name and see if any hidden financial treasures pop up in their database. Finding an old, forgotten pension check can bring an unexpected wave of massive financial relief to a grieving family.
Setting Up a Generational Wealth Meeting
Once the dust finally settles, gather your immediate family for a very serious talk about the future of the settlement. Explain exactly how you plan to invest the money and why you are making those specific financial choices today. This open, honest communication easily prevents greedy relatives from making sudden, unreasonable demands for cash handouts later on.
Treat this family meeting just as seriously as you would look for warning signs before co-signing a loan for a relative. You absolutely have to set firm financial boundaries right away to protect your own mental health. If you hand out money every single time someone asks, the entire settlement will vanish completely in less than a year.
Creating an Emergency Buffer Zone
Before you invest a single dime of the payout into the stock market, you must carve out a large emergency fund. This cash should sit safely in a highly liquid savings account where you can grab it tomorrow if a sudden crisis hits. A solid emergency fund protects you from having to sell your long-term investments when life throws an unexpected curveball.
Think about how terrifying it feels when you can no longer afford your student loan payments during a job loss. A proper emergency buffer completely eliminates that kind of deep financial panic from your daily life forever. It gives you the ultimate, unbeatable freedom to sleep peacefully at night knowing your bills are covered.
Dangerous Pitfalls That Will Destroy Your Settlement
Making honest mistakes is entirely normal, but some errors in estate management carry a highly devastating price tag. I have seen incredibly close, loving families completely tear each other apart over easily avoidable financial misunderstandings. You must absolutely recognize these hidden traps before you accidentally fall right into one and ruin your progress.
The Nightmare of the "Quick Fix" Spending Spree
The single most destructive thing you can do is start spending the money before the massive check actually clears your bank. People often go out and buy expensive new cars or book luxury vacations on credit, assuming the payout will cover it all soon. Then, a sudden legal dispute completely freezes the estate account, leaving them drowning in massive, high-interest credit card debt.
Never count your chickens before they hatch, especially when dealing with massive corporate insurance agencies. Wait patiently until the funds have fully settled in your personal bank account for at least a full week. Managing this extreme patience is similar to taking methodical steps right after a minor car accident—you have to stay perfectly calm and just follow the proper process.
Hiding Documents from Other Beneficiaries
Sometimes, one family member finds the insurance policy first and decides to hide it from everyone else in the house. They mistakenly think they can quietly claim the entire cash amount without their siblings ever finding out about the money. This is actually a severe form of financial fraud, and it almost always ends up in a highly toxic, expensive courtroom battle.
Insurance companies are required by strict laws to notify every single person officially listed on that beneficiary form. Hiding the paperwork only makes you look incredibly guilty and instantly destroys any remaining trust within your family circle. Honesty is not just the best policy here; it is the only legal way to handle the situation properly. For detailed, professional ethical guidelines on estate handling, studying the American Bar Association's guide for executors is an excellent step.
Ignoring the Danger of Outdated Beneficiaries
Imagine discovering that your father's life insurance policy still lists his ex-wife from thirty years ago as the sole recipient of the money. This is an incredibly common, terrifying nightmare because people simply forget to update their paperwork after a major life event like a divorce. If you are reading this right now, please go check your own personal policies immediately to protect your own children.
Once a person passes away, it is virtually impossible to change that beneficiary designation in the eyes of the law. You cannot just call the company and explain that it was an honest mistake on your father's part. It is exactly like finding terrible gaps in your own health insurance plan right after you get extremely sick; the severe damage is already done.
Paying Estate Debts from Your Own Pocket Too Early
When aggressive creditors hear about a death in the family, they immediately start calling the surviving members constantly. They will try their hardest to guilt-trip you into paying off your loved one's medical bills or credit cards using your own personal savings. Do not ever give them a single penny of your own hard-earned money.
These massive debts belong entirely to the estate itself, not to you personally as a grieving family member. If the estate completely runs out of money before all the bills are paid, the remaining corporate creditors simply take a financial loss. If you panic and pay them directly from your personal checking account, you will absolutely never get that money back.
Trying to Play the Role of a Legal Expert
Do not try to interpret complicated legal language by running a quick, basic internet search on your phone. Estate laws change wildly depending on exactly which state you live in, and generic online advice will easily steer you totally wrong. When you misinterpret a specific tax law, the massive financial penalties fall directly heavily onto your own shoulders.
Always rely strictly on actual, licensed professionals to translate the heavy legal jargon for you properly. Just like you rely entirely on uninsured motorist coverage to protect you on the highway, you need a strong legal shield during an estate settlement. It is an upfront, necessary cost that easily pays for itself ten times over by preventing expensive lawsuits from angry relatives.
Failing to Keep Digital Backups
We live in a highly modern world, yet grieving families still rely heavily on a single cardboard box full of fading paper receipts. If a house fire, sudden flood, or simple accident destroys that physical box, your entire claim could be permanently ruined. You absolutely must treat these delicate papers like solid gold bars.
Take highly clear, well-lit photos of every single document, letter, and medical form using your smartphone camera today. Upload these digital files to a highly secure cloud storage service so you can access them instantly from anywhere in the world. The official National Association of Insurance Commissioners (NAIC) strongly advises keeping multiple digital backups of all active life policies to prevent devastating financial losses.
Your Blueprint for Moving Forward with Confidence
Handling a massive family settlement is undeniably one of the absolute hardest things you will ever have to do in your life. It aggressively tests your patience, totally drains your daily energy, and forces you to face complex legal systems while you are actively grieving a massive loss. But I want you to remember closely that you are entirely capable of getting through this dark, stressful tunnel safely.
Every single phone call you successfully make and every document you perfectly organize brings you one huge step closer to absolute financial peace. By staying highly organized and actively seeking professional help, you totally strip the insurance companies of their power to delay your claim. You are no longer a helpless victim of confusing bureaucracy; you are a highly educated, prepared advocate for your family's future.
Take a very deep breath right now, carefully gather your files together, and tackle just one small task on your checklist today. You are actively building a incredibly powerful financial foundation that will actively protect your loved ones for many decades to come.
A Quick Word from My Own Journey: I know exactly how completely suffocating this entire process feels because I lived through those exact same sleepless nights myself. My biggest realization was that asking for professional help is a true sign of strength, not a weakness at all. You have the incredible power to turn this confusing mess into a lasting legacy of true security for your family.
Most Common Questions About Managing Family Payouts
How long does an insurance company have to pay out an estate claim?
Most companies are legally required to process a clean, perfect claim within 30 to 60 days after receiving the official death certificate. However, if they decide to investigate the original policy heavily or request old medical records, the delay can easily stretch into several incredibly long months.
Do I have to pay heavy income taxes on a life insurance settlement?
In the vast majority of normal family situations, basic life insurance payouts are completely free from federal income taxes. You really only have to worry about paying taxes on any extra interest the money earns while it sits safely in your bank account waiting to be spent.
Can an insurance company refuse to pay the named beneficiaries?
Yes, they can legally deny a payout claim entirely if the deceased person blatantly lied about their medical history on the original application. They can also strongly refuse to pay if the person passed away while committing a serious crime or doing something extremely dangerous that violates the specific contract.
What happens if the primary beneficiary passed away first?
If the main person listed on the policy sadly dies before the policyholder, the money automatically goes directly to the named secondary beneficiary. If there is absolutely no backup person listed anywhere on the form, the cash gets dumped directly into the general estate and must go through a long, expensive court process.
Do I need to hire an expensive lawyer to claim an insurance payout?
If you are the absolute only clear beneficiary and the paperwork is perfectly organized, you usually do not need an attorney to get the check. But if angry family members start arguing loudly over the money or minor children are involved, hiring a good legal expert is an absolute must to protect yourself.
Disclaimer: The information provided in this article is for highly educational and informational purposes only and does not constitute official legal, financial, or tax advice. Always consult with a licensed professional or certified attorney in your local jurisdiction before making any major financial decisions regarding estate settlements or insurance payouts.