The Silent Heavy Weight of Post-Graduation Reality
You just walked across the stage, grabbed that expensive piece of paper, and thought you were finally free. But let me guess—instead of celebrating, you are already stressing about the massive student loan bill waiting around the corner. I have been exactly where you are, constantly checking my bank app and panicking about the six-month grace period. Let me show you exactly how to beat this confusing system before it drains your wallet.
For so many of us, graduating is supposed to be this amazing, joyful celebration of freedom. We spend years studying late into the night, passing exams, and dreaming about our bright futures. But the moment we walk across that stage, a heavy dark cloud of financial anxiety starts following us around. The transition from being a student to a fully independent adult hits hard, and it hits fast.
The worst part is the overwhelming confusion. Nobody really sits us down and explains how these complicated government funding systems actually work in the real world. We just sign the digital paperwork when we are teenagers and hope for the best.
Now, the grace period is supposed to be a helpful breathing room. It is designed to give you a temporary break to find your footing. However, for most graduates, it quickly turns into a dangerous waiting game of pure anxiety. You know a massive financial storm is coming, but you just do not know exactly when it will hit or how bad the damage will be.
Your Quick Survival Guide (Read This First):
- Identify your enemy: Unsubsidized accounts grow quietly every single day during your pause.
- Fight the math: Making tiny $10 or $20 payments right now stops interest from permanently sticking to your balance.
- Do not settle: You never have to accept the expensive standard 10-year repayment track if you apply for income-based options.
- Automate to win: Setting up auto-pay usually scores you a quick interest rate discount.
Unmasking the Six-Month Illusion
Let us break down exactly what happens when you finally leave school and enter this waiting phase. Think of the grace period like a giant pause button on a complicated video game. The game itself stops moving forward, but in the background, a massive software update is still downloading without you noticing.
For federal education funding, this pause usually lasts exactly six months. During this exact time frame, the government does not require you to make any official monthly payments. You get a temporary hall pass from your financial obligations.
Most graduates look at this time and think they are completely off the hook. They assume they can just ignore their accounts, travel a bit, or slowly look for a job without any consequences. This is exactly where the biggest financial trap is hiding.
While you are resting, your accounts might be actively working against you. The reality of this situation depends entirely on the specific type of funding you accepted years ago. There is a massive difference between subsidized and unsubsidized accounts, and knowing this difference will literally save your bank account.
The Sneaky Mathematics of Unsubsidized Debt
Here is a simple truth that catches almost everyone completely off guard. If you hold unsubsidized funding, that six-month pause is only pausing your required payments. It is absolutely not pausing the math happening in the background.
Every single day you wake up during those six months, a tiny amount of extra money is being added to your total balance. This happens silently. You do not get a warning text message or a daily email reminding you about it.
Let us look at a highly practical scenario. Imagine you borrowed money to pay for your tuition, and it is entirely unsubsidized. You finish your exams, pack up your apartment, and move back home to save money. For six whole months, you focus entirely on your job hunt and do not log into your financial portal even once.
When you finally get that first official bill in the mail, you will be shocked. The total amount you owe is suddenly much higher than what you actually borrowed. Why? Because the background math never stopped running.
The Danger of the Capitalization Trap
This brings us to one of the most important concepts you need to understand right now. It is called capitalization, and it is a massive wealth killer for young professionals.
When your six months run out, all that extra money that was quietly adding up does not just sit on the side. The system takes all of it and permanently glues it to your original starting balance.
If you are feeling overwhelmed by all these loan terms, take a quick look at this incredible breakdown that completely changed how I view my personal finances.
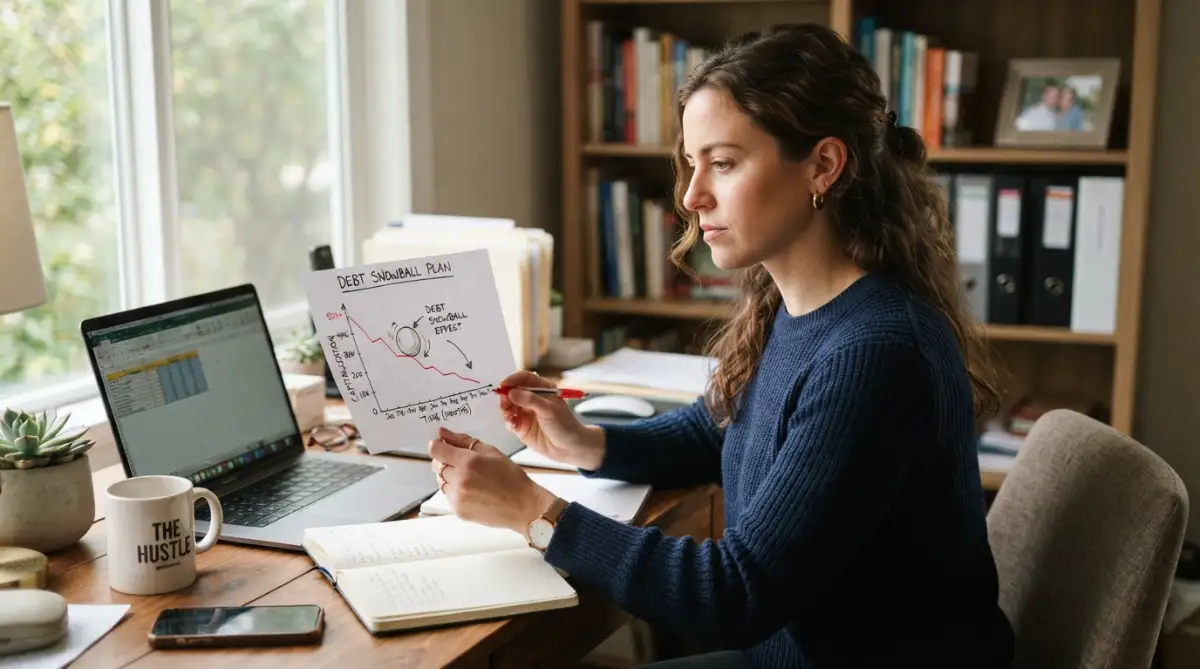
From that exact day forward, you are no longer just paying the math on what you borrowed. You are now paying extra math on top of the extra math. This single event can easily force you to stay in debt for extra years.
My own personal realization hits very close to home on this topic. I completely ignored my unsubsidized loans during my own six-month window because I thought I was protecting my limited cash. If I had just paid twenty dollars a week toward the background math, I would have saved myself thousands of dollars in the long run.
Subsidized Accounts: The Hidden Blessing
Now, let us flip the coin and look at the brighter side of this situation. If your financial aid package included subsidized funding, you have a completely different reality.
With this specific type of funding, the government is actually stepping in and covering that daily background math for you. During your entire six-month window, your total balance stays completely frozen in time.
If you borrowed exactly ten thousand dollars, you will wake up six months later owing exactly ten thousand dollars. This is a massive financial advantage that you need to use wisely.
Here is a simple comparison to keep things crystal clear in your mind:
Real-Life Math Check: The Cost of Waiting
Let me show you a quick example of how this plays out in real life. If you have a $30,000 unsubsidized loan with a 6% interest rate, you are quietly gaining about $4.93 in daily interest. Over a standard six-month pause, that adds up to roughly $900. If you let that $900 stick to your starting balance (capitalization), you will pay interest on $30,900 for the next ten years. Just paying that $4.93 a day right now saves you a massive headache later.
Actionable Moves to Make While the Clock Ticks
Knowing the problem is only half the battle. Now we need to focus on what you should actually do while you are sitting in this six-month waiting room. Do not just wait for the first bill to arrive. Take total control of your situation today.
First, you need to conduct a complete inventory of everything you owe. Log into your official government student aid dashboard. Write down every single account on a physical piece of paper.
You need to clearly label which accounts are subsidized and which ones are unsubsidized. Highlight the unsubsidized ones in bright red ink. These are your most dangerous financial enemies right now.
The Power of Micro-Payments
You do not need a massive six-figure salary to start fighting back during your grace period. One of the smartest things you can possibly do is start making tiny, unofficial payments right now.
Even if you only have a part-time job or are doing freelance work, find a way to spare just ten or twenty dollars a week. Log into your servicer portal and apply that small amount directly to your unsubsidized accounts.
Your entire goal here is to keep that background math from piling up before capitalization happens. Every single dollar you pay right now hits much harder than a dollar paid a year from now. You are essentially fighting the fire before it spreads to the rest of the house.
Building a Buffer Zone
While you are fighting the background math, you also need to protect your immediate future. You must build a small emergency cash buffer before your official monthly bills start arriving.
When the grace period officially ends, your budget is going to take a sudden, hard hit. If your car breaks down or you have a medical emergency in that exact same month, you will be in deep trouble.
Start putting aside a small amount of cash in a completely separate checking account. Tell yourself this money does not exist. This is your safety net for when life throws a curveball at the exact same time your required payments begin.
Exploring Income-Driven Realities
Another massive mistake people make is assuming they have to accept the default payment plan. When your six months end, the system will automatically place you on a standard ten-year track.
For a recent graduate with an entry-level salary, this standard track is usually way too expensive. The monthly bill can easily eat up half of your take-home pay, leaving you struggling to survive.
Do not wait for the bill to arrive to fix this. You can actually apply for different plans before your time runs out. The system offers several tracks based entirely on how much money you currently make.
If you are unemployed or working a low-paying job right now, your required monthly payment on these plans could literally be zero dollars. Yes, you read that right. You can legally owe zero dollars a month while you get your career off the ground.
Quick Pro Tip: When you look into Income-Driven plans, keep an eye out for the newest federal options. Some of these modern plans will actually stop your balance from growing if your calculated monthly payment is too low to cover the background math. It is a fantastic loophole that protects you while you are job hunting!
Myth vs Reality: Navigating Common Confusions
Let us clear up some very common misunderstandings that spread easily among graduates.
Myth: "If I go back to school for a master's degree, I get another full six months when I graduate again."
Reality: You only get one single grace period per funding account in your lifetime. If you already used it up, your payments will start almost immediately after you leave school the second time.
Myth: "Consolidating my accounts right after graduation is always the smartest move."
Reality: If you combine your accounts too early, you instantly throw away any remaining grace period time you had left. Your new combined bill will be due almost right away. Always double-check your timeline before signing consolidation paperwork.
Handling Unpredictable Life Events
Life rarely goes exactly according to our perfectly organized plans. Sometimes, six months is just not enough time to find a stable job in your field.
If you reach month five and realize you absolutely cannot afford the upcoming bill, you need to communicate. Do not hide from your servicer. Hiding and missing payments will destroy your credit score in a matter of weeks.
Instead, pick up the phone and call them directly. Explain your exact situation clearly and honestly. They deal with struggling graduates every single day.
They can offer you tools like deferment or forbearance. These are official ways to pause your payments safely without ruining your financial reputation. However, you must ask for them before you miss a deadline.
The Psychological Shift
Tackling this situation requires a complete shift in how you view your money. You have to stop looking at your education debt as a terrifying monster under the bed.
Treat it like a simple business transaction. You traded future money for current education. Now, it is simply time to balance the business books.
By taking small, deliberate actions during your six-month window, you completely remove the fear from the equation. You transition from being a passive victim of the system to being the active CEO of your own financial life.
Organize your papers today. Make a tiny five-dollar payment tomorrow just to see how the system works. Small actions build massive confidence, and confidence is exactly what you need to win this financial game.
Advanced Strategies to Outsmart the System
Imagine playing a complicated game of chess where you already know your opponent's exact moves six steps ahead of time. This is exactly how you should treat your federal education funding right now. While most of your former classmates are completely ignoring their accounts, you can use this temporary pause to build an unbreakable financial defense.
The biggest secret to winning this money game is realizing that you do not have to wait for official permission to start making progress. The system is designed to keep you comfortable and quiet until the massive bills arrive. By taking offensive action right now, you completely disrupt that expensive cycle.
First, you need to understand the magic of targeted micro-payments. If you have multiple different accounts bundled together, they do not all grow at the exact same speed. Some of your unsubsidized accounts will have much higher interest rates attached to them.
Instead of throwing random amounts of money at your general balance, you must become a financial sniper. Log into your servicer portal and manually direct your small five or ten-dollar payments exclusively toward the account with the highest rate. You can easily find the exact breakdown of your servicer details directly through the Federal Student Aid database, which is the most accurate source for your official records.
By pulling out the biggest financial weeds first, you stop them from stealing all your hard-earned cash. It is extremely satisfying to watch that specific high-rate balance slowly drop while you are not even officially required to pay anything yet.
The Auto-Pay Discount Secret
Here is another brilliant move that almost nobody talks about during the waiting phase. Almost every single government loan servicer offers a hidden reward for setting up automatic payments. They will usually drop your overall interest rate by a quarter of a percent just for giving them your banking details.
Now, a quarter of a percent might sound like a tiny, meaningless drop in the bucket today. However, when you stretch that tiny discount over a standard ten-year repayment timeline, it magically turns into hundreds of saved dollars.
You can set up this automatic system right now, even if your required monthly payment is currently set to zero dollars. You lock in that lower mathematical rate before your grace window even closes. If the thought of doing this makes you anxious, you can always learn the best strategies for managing student loans without fear to build up your confidence.
Building Your Post-Graduation Financial Fortress
Another incredibly smart strategy is the "Phantom Payment" method. Let us say you calculate that your future monthly bill will be around two hundred dollars. Do not wait six months to see how that feels in your budget.
Start paying that exact two hundred dollars to yourself right now. Open a completely separate high-yield savings account and transfer that money over on the first day of every single month. You are basically tricking your brain into getting used to the smaller paycheck.
If you can easily survive on your income minus that phantom payment, you are completely ready for the real thing. If you struggle to buy groceries, you now have several months to find a side hustle or negotiate a better payment plan before it actually matters.
As a massive bonus, that separate savings account will grow into a beautiful emergency fund. When life throws sudden expensive problems at you, you will not have to panic. For instance, if you suddenly face medical issues, having this cash buffer protects you from the hidden gaps in your health insurance plan.
The Tax Deduction Advantage
Here is an advanced tip that will make you feel like a true financial genius when spring arrives. Any extra money you pay toward your background interest during this waiting phase might actually come back to help you during tax season.
The government actually rewards people who actively pay down their education debt. You can often deduct the exact amount of interest you paid from your total taxable income for the year. This specific strategy is clearly outlined by the Consumer Financial Protection Bureau (CFPB) guidance on education debt, which provides excellent free resources for young adults.
Keep a highly detailed record of every single micro-payment you make right now. When you file your taxes next year, you can hand that information to your accountant. It feels amazing to turn a stressful debt payment into a strategic tax advantage.
The Most Dangerous Traps Graduates Fall Into
While it is great to focus on winning strategies, we also need to have a very serious conversation about losing. This specific six-month window is basically a minefield of bad financial decisions. I have seen incredibly smart, hard-working people completely ruin their financial futures because they stepped on an avoidable trap.
The most common and destructive mistake is what I call the "Head in the Sand" syndrome. Young adults are completely terrified of the total number they owe, so they just pretend the debt does not exist at all. They delete emails from their servicer, throw physical letters in the trash, and never answer unknown phone calls.
This behavior is completely financially lethal. Your servicer is not trying to annoy you; they are often trying to warn you about upcoming deadlines or missing paperwork. If you ignore them, you might completely miss out on special forgiveness programs or income-driven plans that you actually qualify for.
The Lifestyle Creep Disaster
Another massive pitfall happens the exact second a graduate gets their first professional paycheck. After eating instant noodles for four years, holding real money feels like winning the lottery. They immediately sign a lease for an expensive downtown apartment and finance a brand-new car.
They completely forget that a massive monthly education bill is secretly waiting in the shadows. When month seven finally arrives, their new expensive lifestyle instantly crashes into a brick wall. They have zero dollars left in their budget to pay the government.
This exact scenario often leads graduates to beg their parents for emergency financial help. This creates massive family tension, which is exactly why you must strictly observe the warning signs before co-signing a family loan. Do not drag your loved ones into a mess that could have been avoided with simple planning.
The Scam Industry Threat
When you are desperately looking for an easy way out of debt, you become a massive target for scammers. The internet is heavily flooded with fake companies promising to completely erase your education debt in twenty-four hours. They use very official-sounding names and demand massive upfront fees for their secret services.
Please listen to me very carefully right now. There is absolutely no secret magic trick to making government debt disappear overnight. If a random company texts you offering instant forgiveness for a fee, it is a complete lie.
Always protect your personal information and verify these bold claims through the official Federal Trade Commission (FTC) guide on avoiding debt scams. Never ever give a third-party company your official government login passwords.
Ignoring Real-World Surprises
The final trap is assuming that nothing bad will happen during your six-month waiting phase. You might perfectly calculate your future budget, but real life is entirely unpredictable. Accidents happen, cars break down, and unexpected bills always seem to show up at the worst possible time.
If you are just driving to your new entry-level job and someone hits your car, your entire financial plan can fall apart in seconds. This is why understanding how to handle sudden chaos, like knowing the exact steps to take immediately after a minor vehicular accident, is just as important as reading your loan documents.
You must protect yourself from all angles. A smart financial plan does not just look at education debt in a lonely bubble. It also looks at how you would survive a sudden emergency without putting your car repair on a high-interest credit card. For example, understanding how uninsured motorist coverage saves you money can literally save your entire debt repayment strategy from collapsing overnight.
Your Personal Action Plan for Tomorrow Morning
We have covered a massive amount of information today, and your brain might be spinning right now. Please take a deep breath and relax your shoulders. You do not have to fix your entire financial life in one single afternoon.
The difference between successful people and those who stay broke is simply taking tiny, consistent actions. Your only goal right now is to transform this heavy anxiety into focused, intentional power. Let us create a very simple checklist that you can easily finish tomorrow morning while drinking your coffee.
First, you are going to find your official login details for your servicer portal. Reset the password if you forgot it, and just log in to look at the main dashboard. You do not even have to make a payment yet; just look the monster directly in the eyes.
Taking Back Your Power
Second, you are going to find a physical notebook and a pen. Write down exactly how much of your total balance is unsubsidized. Circle that specific number in red ink and put the notebook directly on your desk where you will see it every day.
Third, you are going to set up a calendar reminder on your phone. Count exactly five months from your official graduation date and create an alarm called "Decision Day." This gives you a strict personal deadline to choose an income-driven repayment plan before the automatic system traps you.
As you grow older, this single experience will teach you how to handle much bigger financial decisions down the road. The money management skills you build right now will protect you later when you are dealing with mortgages or uncovering the truths about outliving your term policy. Every step you take today makes your future completely unshakable.
Common Questions About Your Payment Pause
Does the waiting window start completely over if I decide to go back to school?
No, you only get one single full grace period for each specific funding account in your entire life. If you use it all up now and go back for a master's degree later, your required payments will start almost immediately after you leave school the second time. You must plan your future studies with this strict timeline in mind.
Can I legally make unofficial payments while the six-month pause is active?
Yes, you absolutely can, and it is the smartest financial move you can possibly make. Any money you send during this time usually goes directly toward fighting the daily background interest on your unsubsidized accounts. This actively prevents your total balance from magically growing larger before the official bills arrive.
What exactly happens if I cannot find a job when the time finally runs out?
The government system has specific safety nets built in, but you have to actively ask for them before you miss a deadline. You can apply for an income-driven plan where your required monthly bill could literally be zero dollars based on your current unemployment status. If things get extremely tough, you can also request a temporary official pause called a forbearance.
Will my personal credit score drop during this waiting time?
Your credit score is completely safe during this official six-month window because you are not missing any required payments. The accounts will simply show up on your credit report as being in good standing. However, the second that window closes, a single missed payment will severely damage your score in a matter of weeks.
I completely understand how heavy this burden feels right now, but I promise you have the power to fix this. My own financial journey was messy and scary at first, but taking that single small step of logging into my account completely changed my life. You are entirely capable of turning this stressful situation into a massive personal victory, so start taking control today!
Disclaimer: The information provided in this article is for general educational and informational purposes only and does not constitute professional financial, tax, or legal advice. Every individual's financial situation is entirely unique. Please consult with a certified financial planner or a professional loan advisor before making any major decisions regarding your personal education debt or long-term financial strategies.